Nexo sits in a different category from a simple instant swap desk. It is a crypto financial platform built around interest products, collateralized credit, a card, and an in-app exchange. That breadth is its appeal. Somebody holding BTC, ETH, stablecoins, or a diversified long-term portfolio can keep several parts of their crypto life under one roof rather than shuttling coins between a lender, exchange, and card provider.
The company launched in 2018 and made its name through crypto-backed loans. Its proposition remains easy to understand: deposit eligible assets, borrow against them without selling, and repay later. For investors who are convinced they do not want to dispose of a position during a downturn, that can be genuinely useful. It is also a product that requires discipline. Borrowing against volatile collateral is not free money, and users who treat it that way can be forced into a painful repayment or liquidation event.
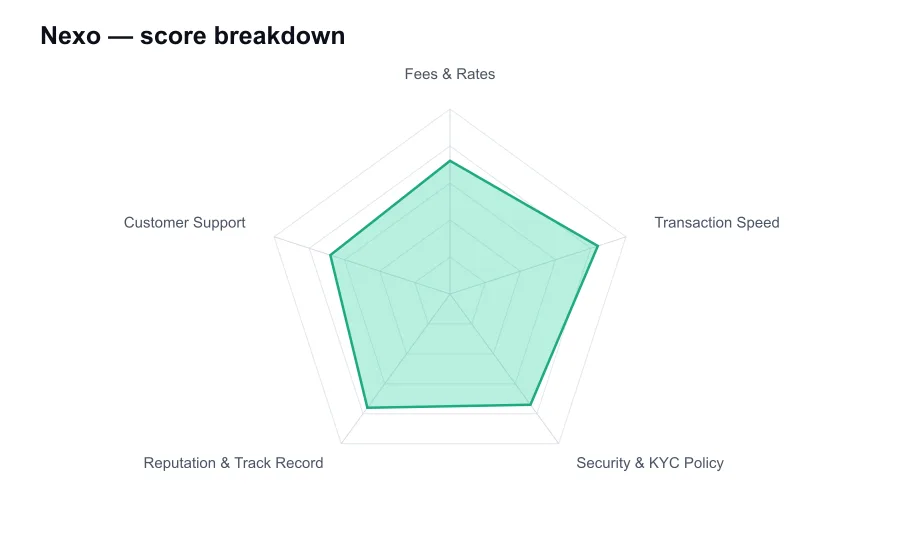
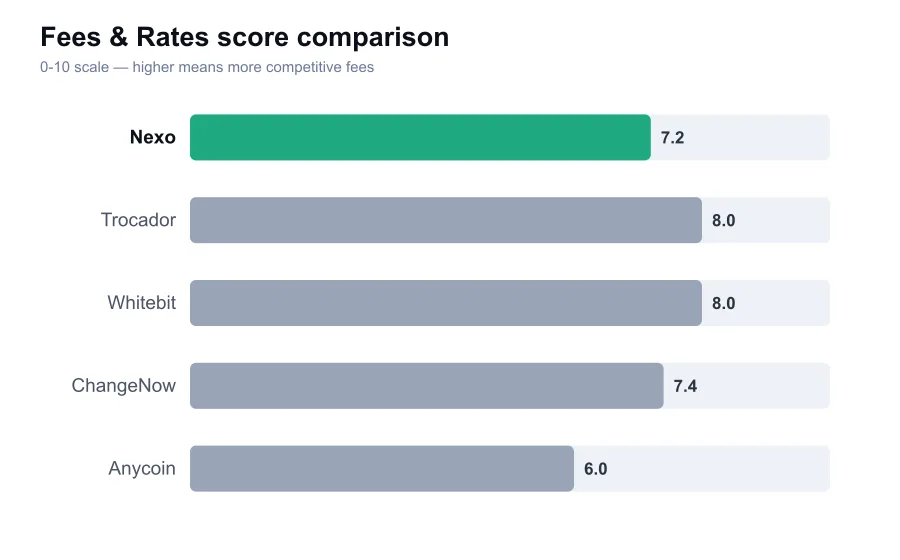
Nexo's exchange is convenient rather than a serious trader's first choice. Standard published pricing has generally been around 0.20 percent maker and 0.25 percent taker, with lower fees available through loyalty tiers and NEXO token holdings. Those numbers are respectable for a built-in retail exchange, though they do not beat the deepest order-book venues. Binance, Kraken Pro, and Coinbase Advanced give active traders more granular control and often better execution conditions.
The bigger cost question is not the headline trading fee. It is spread. Nexo's swap interface is designed for speed and simplicity, but users exchanging a thinly traded token or making a large market order should compare the quoted result against a liquid external exchange. The platform shows the conversion before confirmation, which helps, but it does not change the fact that convenience usually carries an execution premium.
Card spending and lending costs are more complicated than exchange fees. Loan rates depend on the customer's loyalty tier, loan-to-value ratio, and collateral type. The best advertised rates are reserved for users meeting specific conditions, often including NEXO token exposure. That structure is common in crypto finance, but I dislike how easily a promotional starting rate can become the number readers remember. Prospective borrowers should model the ordinary rate they will actually pay, not the lowest figure on a marketing page.
Transfers are quick where Nexo controls the ledger. Internal account movements and exchanges are normally near-instant, while blockchain withdrawals depend on the asset, network congestion, and compliance checks. In everyday use, the app is responsive and the exchange settles promptly. That is a real advantage over manual swaps between wallets. It should not be mistaken for instant settlement on-chain, particularly for Bitcoin or an Ethereum transaction during a busy period.
Nexo has maintained a polished mobile and web experience. The dashboard is easier to understand than many lending platforms, and the collateral view makes the health of a credit line reasonably visible. Still, the sheer number of products can tempt people into clicking before reading. A loan, leveraged exposure, and yield product may all look like ways to make idle crypto work, but their risks are not remotely identical.
On security, Nexo presents a stronger operational picture than a small anonymous swap site. It has stated that it uses institutional custody arrangements, cold storage, encryption, multi-factor authentication, and transaction monitoring. Users can enable 2FA, and they should do so immediately. The company has also used third-party attestation and reserve-related reporting initiatives, although readers should not confuse an attestation with a full independent audit of every liability and risk scenario.
The KYC policy is not optional in practice. Nexo is a regulated-facing centralized provider, and identity verification is part of using its core services. This will frustrate privacy-first users, but it is preferable to vague compliance rules that suddenly freeze an account after deposits arrive. Verification can still take longer during busy periods or where source-of-funds documents are requested, so do not open an account minutes before you need access to capital.
Nexo's record is mixed in the way many surviving centralized crypto firms are mixed. It weathered the 2022 lending crisis that destroyed Celsius, BlockFi, and Voyager, which matters. It also faced regulatory pressure, including a major settlement with US regulators over its Earn Interest Product and an exit from the US retail market. Survival is meaningful, but it is not proof that counterparty risk has disappeared.
That history should make customers more cautious, not necessarily dismissive. Nexo is not an unregulated fly-by-night operation, yet assets deposited there are still exposed to the company's custody, business decisions, and legal environment. The sensible use case is active capital management, not storing every satoshi you own indefinitely. Self-custody remains the cleaner answer for coins intended as long-term savings.
Support is available through in-app chat and ticket channels, with automated assistance handling the first layer. Straightforward questions about deposits, swaps, and account settings usually have a clear help-centre trail. More difficult cases, especially compliance reviews or a transfer requiring manual investigation, can feel slow and procedural. That is not unique to Nexo, but the more money involved, the less comforting a chatbot becomes.
Nexo's customer service reputation also reflects a recurring centralized-finance tension. Happy users tend to report a smooth experience because everything happens quickly until it does not. Unhappy users often arrive at support after a verification hold, withdrawal review, or collateral issue, exactly when speed matters most. The company could improve trust by giving clearer case updates and more transparent escalation expectations.
The NEXO token is another point where I would urge restraint. Holding it may improve loyalty-tier economics and can make the platform's pricing look much better. But it also concentrates a user's financial exposure. If you hold NEXO, borrow from Nexo, and keep collateral at Nexo, a problem affecting the business can hit several parts of your balance sheet at once.
For ordinary spot buyers, Nexo is rarely the cheapest route into crypto. For people who value a coherent account, a card, flexible portfolio tools, and the option to borrow against established coins, it remains one of the more credible names in a difficult sector. Its strengths are convenience, product depth, and a better-than-average survival record. Its weakness is the same thing that defines the product: you are trusting a centralized financial intermediary with volatile assets.
My view is that Nexo is useful, but only if you understand exactly why you are using it. Keep a conservative loan-to-value ratio, turn on every security control, and compare exchange quotes for meaningful trades. The platform earns a solid rating because it has real infrastructure and has outlasted weaker rivals. It does not earn a blind trust rating, because no crypto lender should.